GUTSCHEIN
Bitte haben Sie einen Moment Geduld, wir legen Ihr Produkt in den Warenkorb.
Diese Produkte könnten Sie auch interessieren:
Auch verfügbar als:
Bitte haben Sie einen Moment Geduld, wir legen Ihr Produkt in den Warenkorb.
| Themen | Mathematik und Naturwissenschaften Mathematik |
|---|---|
| ISBN | 9783764365530 |
| Sprache | Englisch |
| Erscheinungsdatum | 01.06.2001 |
| Größe | 241 x 160 mm |
| Verlag | Birkhäuser |
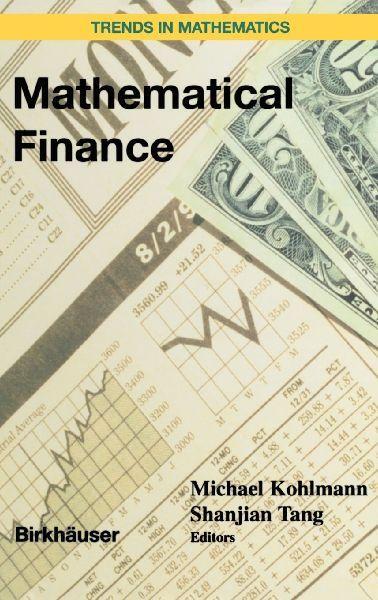
| Herausgegeben von | Tang Shanjian, Michael Kohlmann |
| Lieferzeit | Lieferung in 7-14 Werktagen |
| Herstellerangaben | Anzeigen Europaplatz 3 | DE-69115 Heidelberg ProductSafety@springernature.com |
Note: in the titles of co-authored papers the lecturer's name is in bold face).- Preface.- Participants.- On-line portfolio strategy with prediction.- Continuous time financial market, transaction cost and transaction intensity.- Demand Heterogeneity and Price Volatility.- Optimal default boundary in a discrete time setting.- An Infinite Factor Model for the Interest Rate Derivatives.- Arbitrage and Pricing with Collateral.- On the existence of optimal controls for a singular stochastic control problem in finance.- A Quadratic Approach To Interest Rates Models In Incomplete Markets.- Risk Sensitive Asset Management: Two Empirical Examples.- Bounded Variation Singular Stochastic Control and Associated Dynkin Game.- Option Pricing and Hedging Under Regular Lévy Processes of Exponential Type.- Installment Options and Static Hedging.- Fractional Brownian Motion and Financial Modelling.- Stochastic Volatility and Epsilon-Martingale Decomposition.- Mutual Debts Compensation as Graph Theory Problem.- First Steps to Stochastic Finance.- Fractional Calculus and Continuous-Time Finance III: the Diffusion Limit.- Passport Options Outside the Black Scholes World.- New Developments in Backward Stochastic Riccati Equations and Their Applications.- Quantile hedging for a jump-diffusion financial market model.- Exponential formula and Girsanov theorem for mixed semilinear stochastic differential equations.- An introduction to optimal consumption with partial observation.- Continuous Time CAPM, Price for Risk and Utility Maximization.- LQ control and mean-variance portfolio selections: The stochastic parameter case.- Liquidity Risk in Energy Markets.- Riccati Equation and Viscosity Solutions in Mean Variance Hedging.- A Minimal Financial Market Model.- A note on equivalentmartingale measures with bounded density.- Local optimality in the multi-dimensional multi-period mean-variance portfolio problem.- Transaction Processes among Autonomous Traders.- The Laplace transform approach to valuing exotic options: the case of the Asian option.- Reversible Real Options.- A Toolbox for Generalized Relative Entropies, EMM and Contingent Claim Valuation.- Incremental Value-at-Risk: traps and misinterpretations.- On option expected returns.
| Themen | Mathematik und Naturwissenschaften Mathematik |
|---|---|
| ISBN | 9783764365530 |
| Sprache | Englisch |
| Erscheinungsdatum | 01.06.2001 |
| Größe | 241 x 160 mm |
| Verlag | Birkhäuser |
| Herausgegeben von | Tang Shanjian, Michael Kohlmann |
| Lieferzeit | Lieferung in 7-14 Werktagen |
| Herstellerangaben | Anzeigen Europaplatz 3 | DE-69115 Heidelberg ProductSafety@springernature.com |
Wie gefällt Ihnen unser Shop?
